When Fast Inventory Turnover Looks Like Good News
A company reports that inventory turns rose sharply, and the market reads the change as proof that products are moving faster. The balance sheet appears leaner, less cash is tied up in stock, and management can point to improved efficiency. That reaction may be justified, but the ratio does not explain why inventory declined or sales accelerated.
Fast turnover can reflect strong demand and disciplined purchasing. It can also result from stock shortages, unusually low inventory, falling product variety, or accounting choices that reduce the reported balance. The cost of a rushed conclusion is real: investors may approve a valuation that assumes durable growth, while customers are already facing delays and missed purchases. The ratio earns attention first, confidence later.
Start With the Business Model, Not the Benchmark
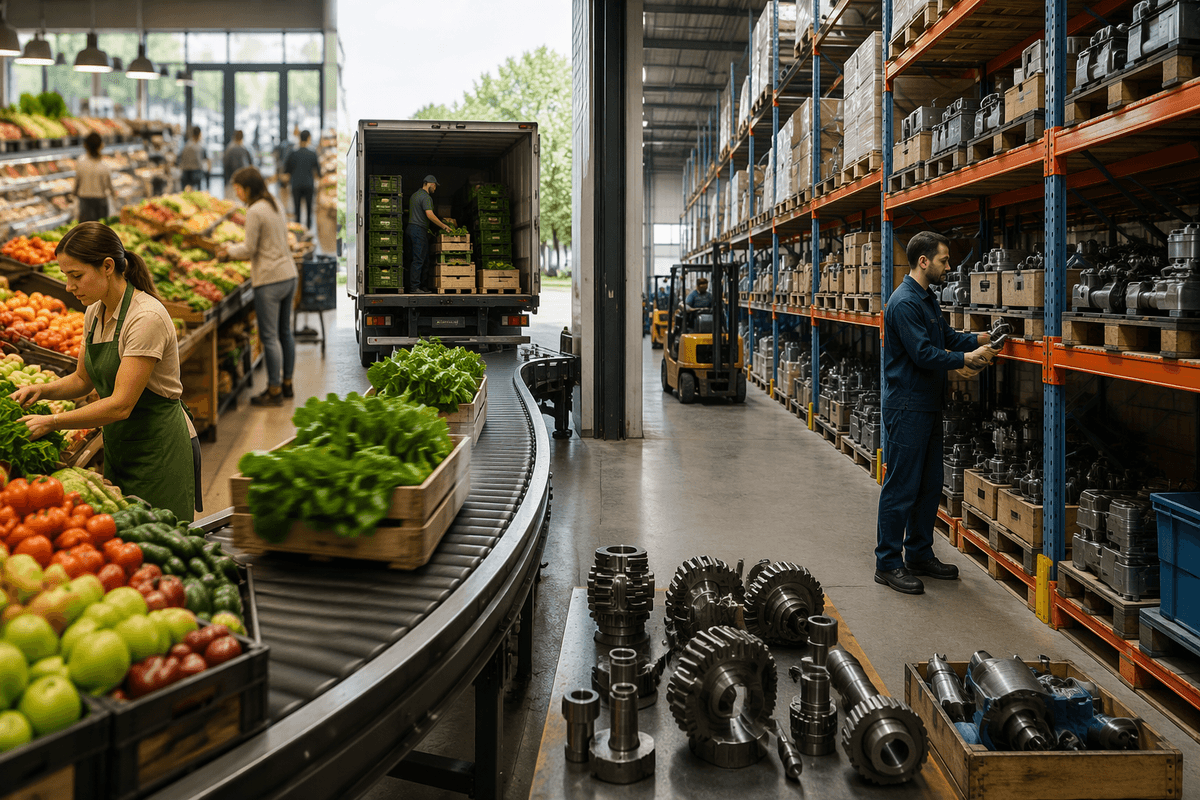
The first comparison should be with the way the company actually makes money. A grocery chain may turn inventory rapidly because products are perishable and replenished daily, while an industrial supplier may hold specialized parts for months before a customer places an order. Applying the grocery chain’s benchmark to the supplier would make normal operating needs look like inefficiency. The same distortion appears across fashion, construction, software hardware, and seasonal businesses.
Business model differences affect both the numerator and the balance-sheet timing behind the ratio. A distributor with broad product availability may accept slower turns to protect customer relationships, while a discount retailer may push inventory out quickly through lower prices and thinner margins. Location, lead times, customization, supplier reliability, and seasonality matter as much as the reported percentage. The useful question is not whether turnover beats an industry average in isolation, but whether it fits the company’s sales cycle and service promise. A comparison becomes meaningful only after accounting for what customers expect to find in stock, how quickly suppliers can respond, and what margin the business earns for carrying that inventory.
A Higher Ratio Can Hide a Weaker Customer Experience
That service promise can deteriorate even while the ratio improves. A retailer may reduce inventory by carrying fewer sizes, colors, or replacement parts, then report faster turnover because the remaining stock sells quickly. The financial statement looks cleaner, but customers encounter empty shelves, longer delivery times, or fewer choices. Lost purchases may not appear immediately in revenue, especially when buyers postpone orders or switch suppliers without making a visible complaint.
Short-term promotions can create the same impression. Discounting slow-moving goods may clear warehouses and lift turnover, but the improvement comes with lower prices, weaker margins, or higher return rates. In a business that competes on availability, the cost may also show up in expedited shipping and emergency purchasing. Investors should therefore compare turnover with fill rates, back-order levels, product availability, returns, and customer retention where those measures are disclosed. A higher ratio deserves less credit when it depends on making the catalog smaller or the customer wait longer. Efficient inventory supports sales; inventory reduction that limits the sale is a different outcome.
Check Whether Sales And Margins Tell The Same Story
The next test is whether the turnover improvement is supported by the income statement. If sales rise alongside inventory turns, the company may be selling more product with less capital tied up. But if turnover increases while revenue is flat or falling, the ratio may reflect inventory cuts rather than stronger demand. That distinction matters when management is presenting the change as an operating improvement. A shrinking product range, delayed purchases, or a weak quarter can produce the same balance-sheet result.
Margins add another check. Higher turnover paired with stable or improving gross margins suggests the company is moving inventory efficiently without giving away too much value. Higher turnover with sharply lower margins may point to clearance pricing, heavier promotions, or a shift toward cheaper products. The timing can also mislead: a discount campaign may improve quarter-end inventory figures while leaving lower-quality earnings behind. Compare revenue growth, gross margin, markdowns, returns, and product mix over several periods. When those measures disagree, turnover is not proof of strength; it is a signal to investigate before relying on the valuation.
Follow Inventory Through Operating Cash Flow
Cash flow shows whether the reported inventory improvement released cash or merely changed the appearance of the balance sheet. When inventory falls and operating cash flow strengthens, the company may be selling existing stock faster, ordering more carefully, or collecting cash without replacing inventory at the same pace. That can support a stronger cash position, but timing matters. A business may temporarily delay purchases before a reporting date, making one quarter look better while creating shortages or larger supplier payments later.
Operating cash flow can also weaken even when turnover rises. Heavy discounting may reduce inventory but leave less cash per sale, while growing accounts receivable can absorb the cash supposedly freed from stock. Compare inventory changes with operating cash flow, accounts receivable, accounts payable, and capital spending across several periods. A persistent cash benefit is more convincing than a single release caused by seasonal buying patterns or payment timing. If turnover improves but cash remains weak, the ratio has not yet proved that working-capital management is creating economic value. It may simply be recording a temporary reduction in stock.
One Period Is Evidence, Not Yet A Trend
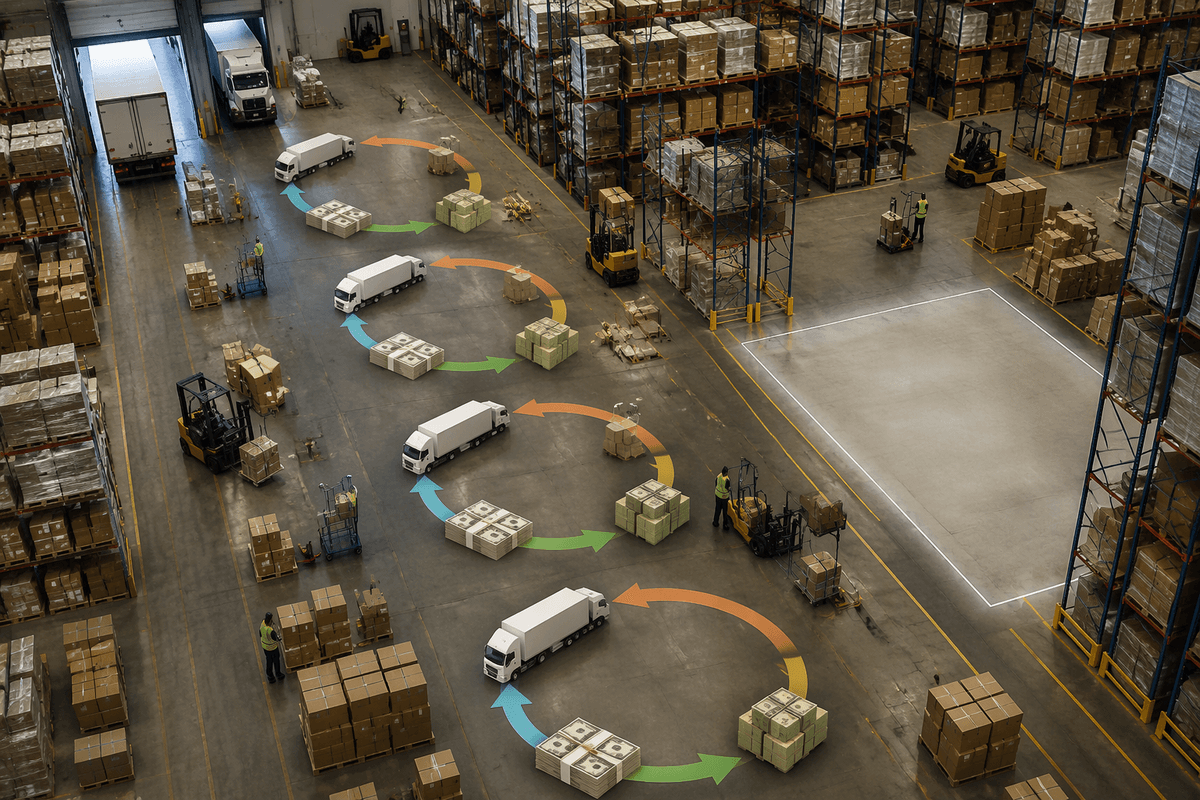
That cash benefit still needs to survive the next reporting periods. Inventory turnover can improve because a company enters a seasonal peak, delays replenishment, or works through an unusually large opening stock balance. None of those conditions necessarily describes its normal operating performance. Comparing only two periods creates a timing problem: the starting inventory balance may reflect a prior buildup, while the ending balance captures a temporary cleanup.
A more reliable review tracks turnover, sales, gross margin, inventory levels, and operating cash flow across several quarters and, where possible, a full business cycle. Look for the same relationship to repeat without rising stockouts, deeper discounts, weaker margins, or strained supplier payments. A reversal does not automatically invalidate the earlier improvement, but it narrows what can reasonably be claimed. One strong period is useful evidence of a change; it is not yet proof that the company has permanently improved how it buys, sells, and funds inventory.
Use Turnover To Ask Better Valuation Questions
Once the trend has been tested, turnover becomes more useful as a valuation question than as a standalone score. Does the company deserve a higher multiple because it generates sales with less inventory, or is the market already pricing in an improvement that depends on discounts, stockouts, or unusually favorable timing? The answer should connect turnover with revenue growth, margins, operating cash flow, and the reliability of future demand.
A strong ratio may support valuation when it repeats across business cycles without weakening customer service or cash generation. A sudden improvement deserves more caution when the share price assumes permanent efficiency but the evidence covers only one period. Turnover can narrow the valuation debate, not settle it: the key question is whether better inventory management will produce durable earnings and cash, rather than simply make one balance sheet look cleaner.